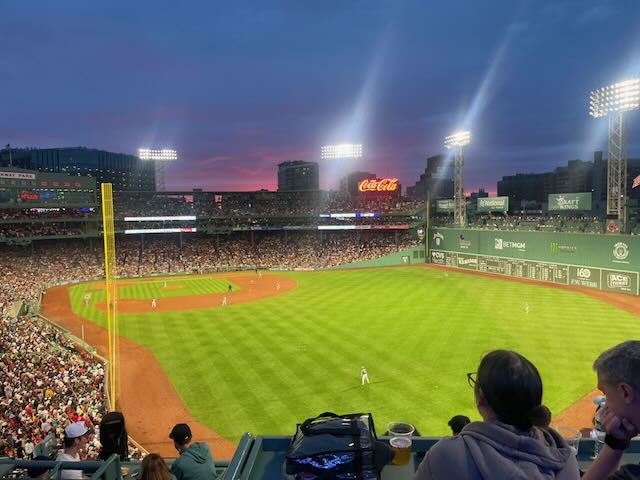
As a lifelong Boston sports fan, I’ve learned there’s one thing you should never do: declare a season over too early. Just a few months ago, the Red Sox looked cooked/finished. They had fallen to 14 games under .500, sports radio was calling for sweeping changes, and many fans had already shifted their attention to Patriots training camp; then something remarkable happened.
The Red Sox didn’t blow up the roster or mortgage the future for a handful of superstars. Instead, they put together one of the most incredible stretches in franchise history: a 15-game winning streak that tied the club record, followed by an astonishing 27 wins in 30 games. Along the way, they weren’t simply beating struggling teams. They swept some of baseball’s best clubs and suddenly looked like an entirely different organization.
As I write this article, the Sox are sitting 14 games above .500 and almost certainly locked into the 3rd wild-card seed, potentially the 2nd. Oh yeah, and the beloved character that is Payton Tolle just pitched an immaculate inning! The BoSox’s mid-season turnaround got me thinking about something I see all the time when giving financial planning advice.
Financial Portfolio Evolution: Sometimes the Right Pieces Are Already There
The easiest conclusion would be that the Red Sox suddenly became more talented; well, they didn’t. Most of the players were the same ones everyone had been criticizing and wanting to dump like yesterday’s garbage just a few weeks earlier. What changed was how those players worked together.
The team roles became clearer and confidence grew. The lineup found its rhythm, and what was once individual talent became collective success. Financial plans can work the same way. People often come into my office assuming they need an entirely new investment strategy. In reality, many already have solid building blocks. They have retirement accounts, taxable investments, emergency savings, insurance, and perhaps even real estate- the whole gamut.
The challenge isn’t always what they own; it’s that those assets aren’t working together with a unified purpose.
Great Coaches Maximize Existing Talent
One of the things I admire most about successful coaches is their ability to maximize the players already in the clubhouse. Chad Tracy wasn’t given a wonderful spot to fill when the team decided it was time to move on from Cora, but he was able to find new breath and get positive returns on what was already in the clubhouse. The same principle applies to investing.
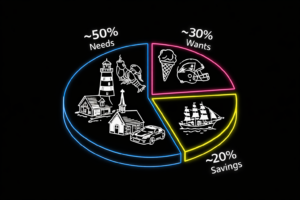
I spend much of my time helping clients organize what they already have instead of constantly searching for something new. Sometimes a few thoughtful adjustments can have a much bigger impact than completely starting over. That’s one reason I reference my Three Bucket Strategy. Every investment should have a purpose. Some assets are designed to generate long-term growth while others help provide retirement income. Others create flexibility for taxes or unexpected expenses. Owning good investments is only part of the equation; getting them to work together is where thoughtful planning begins.
Don’t Let Panic Make the Decisions
If the Red Sox had torn apart the roster after that rough start, this historic run probably never would have happened; again, the same is often true in investing. I see many of the biggest financial mistakes happen when emotions take over. Markets decline (talking heads talk), and suddenly selling feels like the safest decision. But as I’ve stated before, history suggests otherwise!
Many of the market’s strongest days have come shortly after its weakest/regrettable ones. Investors who panic during difficult stretches often miss the recovery they were waiting for. It’s similar to what I discussed in my article about staying invested during market volatility. Boston sports fans who stayed loyal through long championship droughts eventually experienced one of the greatest runs in professional sports history. Patience rewards those who stick with a well-built plan.
“All Set” Isn’t the Same as Optimized
A core philosophy and principle of mine you’ll see throughout my writing is the difference between being all set and being optimized.
Being all set means you’ve accumulated investments, but being optimized means those investments work together toward a common goal. That’s what impressed me most about this Red Sox team: they didn’t suddenly become loaded with new All-Stars; they simply found a way to maximize the talent they already had. I think that’s an encouraging lesson because meaningful progress doesn’t always require dramatic (on-demand) change.
As a family financial planner serving Boston, Newburyport, and the North Shore, I see this every day. Clients often don’t need to start over; they just need their existing investments, tax strategy, and retirement planning to work together more effectively.
The Red Sox reminded us that sometimes the biggest turnaround isn’t about finding new talent, but helping the talent you already have reach its full potential.
If you’d like to talk post-season scenarios or investment portfolios, please book an appointment; my door is always open.
Book an appointment with Scott.
Securities offered through LPL Financial, Member FINRA / SIPC. Investment Advice offered through Flagship Harbor Advisors, a registered investment advisor. Thrive Wealth Strategies and Flagship Harbor Advisors are separate entities from LPL Financial.
The opinions voiced in this material are for general information only and are not intended to provide specific advice or recommendations for any individual.