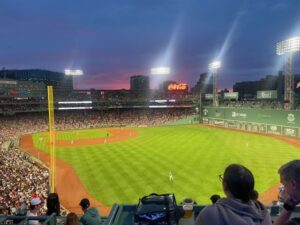
As a lifelong Boston sports fan, I genuinely believe October could be the greatest month on the sports calendar. That is, IF (big if) everything falls into place. If the fates allow it, we could have the Red Sox playing postseason baseball, the Patriots charging into the middle of their season, and the Celtics and Bruins getting things started in fun fashion. If it happens, it’s a cosmic ballet of sports pleasures, though that’s no guarantee.
Think about that for a second. Four major sports, four Boston teams, and potentially four reasons not to make any plans that involve leaving the couch. Of course, the stars don’t align like that every year.
Sometimes the Red Sox are cleaning out their lockers before October even arrives, as they are this season! The Patriots might be building towards another Super Bowl appearance, the Bruins could be figuring things out with a new captain, and the Celtics might need a few weeks to find their new rhythm.
But here’s my point: that’s part of what makes Boston such a great sports city! We don’t need every team to be great at the same time to have something worth cheering for. And believe it or not, a pretty good financial planning lesson is buried somewhere between Fenway Park, Gillette Stadium, and the Garden.
Why Diversification Makes Boston Sports So Much Fun
Imagine if Boston only had one professional sports team. Every year, our entire sports experience would depend on that team’s success. Have a great season? Fantastic. Have a terrible one? Well, I guess we’re waiting until next year—a feast-or-famine type of arrangement.
Fortunately, we’ve got options. Some years belong to the Red Sox. Other years, the Celtics make a championship run. The Patriots have certainly given us our share of memorable seasons, and the Bruins have had plenty of moments when they carried the city’s championship hopes. We never really know which team will deliver the most excitement in a given year. And we don’t have to. That’s the beauty of diversification.
Investors often ask which stocks, funds, or sectors I think will perform best over the next year. It’s a reasonable question, but my response is usually another question: Why should you have to know?
A thoughtful/insightful portfolio diversification strategy isn’t necessarily designed around predicting the next big winner. It’s about building a portfolio with different investments that serve different purposes. When one area of the market struggles, another may perform better. Stocks, bonds, cash, and other investments don’t always respond to economic conditions in the same way.
Of course, diversification doesn’t guarantee profits or prevent losses. Unlike sports teams, different investments can all struggle at the same time. But a well-constructed mix can reduce the risks of relying too heavily on one investment or asset class.
I’ve discussed this concept before in my article on asset allocation strategy; the goal isn’t simply to own a collection of investments. It’s to understand how those investments complement one another and contribute to your financial objectives.
Sometimes the Right Investment Is Playing at the Wrong Time
An investment can be perfectly reasonable on its own and still be poorly suited to the person holding it. Consider a 25-year-old who has decades before retirement. If they’re automatically placed into a conservative allocation with substantial bond exposure, I’d want to understand why. With a long investment horizon, they may be able to accept more short-term volatility to pursue long-term growth.
Now, on the opposite end of the spectrum, consider an 80-year-old who wants to put a substantial portion of their savings into a speculative investment because they’re excited about a company like SpaceX. That doesn’t automatically mean they should avoid growth investments or emerging opportunities. But I’d certainly want to ask how that investment fits their income needs and broader financial plan.
Bottom line: the same portfolio diversification strategy shouldn’t automatically apply to both investors.
My Crusade Against Cookie-Cutter Financial Planning
One thing I’ve become increasingly outspoken about is the tendency to put investors into standardized portfolios based almost entirely on their age. You know the approach. You’re 25, so here’s your portfolio. You’re 55, so here’s another one. Are you 75? Congratulations, we’ve got a different mix ready for you!
Target-date retirement funds and other age-based investment solutions can be useful starting points, as they’re convenient and provide diversification, which is certainly better than having no strategy at all. But convenience and optimization aren’t the same.
Two 55-year-olds might have completely different financial situations. One may plan to retire at 60, while another loves their career and intends to work until 70. One may have a pension, while the other depends entirely on investment income. One might have substantial savings outside their retirement accounts, while another has most of their wealth tied up in a 401(k).
Why should those two people automatically have the same investment allocation? Well, they shouldn’t! That’s why I spend so much time discussing financial planning advice in the context of someone’s entire financial situation, not just their age.
Portfolio Diversification Strategy – “All Set” Isn’t Optimized
If you’ve read my previous articles, you’ve probably noticed that I keep coming back to one of my favorite principles: being all set isn’t the same as being optimized.
Being all set might mean you contribute regularly to your 401(k), have accumulated investments, and have a diversified portfolio. That’s a great start, but being optimized means taking another look and asking whether those investments are positioned appropriately for your circumstances today.
Maybe you’re taking more risk than you need to. Maybe you’re not taking enough. Perhaps your retirement accounts and taxable investments unintentionally overlap, or your portfolio hasn’t evolved as your financial responsibilities have changed.
These are the kinds of things I look for when helping clients think through portfolio evolution and review investment management strategies; not every financial decision requires a dramatic change, just as not every struggling sports team needs to fire its coach or trade half its roster, but it’s always good to evaluate where things are and where they are most likely headed.
Build a Portfolio That Can Compete Every Season
As much as I’d love to see the Red Sox playing meaningful baseball while the Patriots, Celtics, and Bruins are all rolling, I know better than to expect that every October. That’s what makes those rare stretches when everything comes together so memorable. But even when one team disappoints, another might surprise us. And sometimes the team nobody expected much from becomes the one we’re all talking about.
A good financial strategy should embrace that same idea without relying on anyone to predict the future. You don’t need every investment to outperform at the same time. You need a thoughtful mix of assets that supports your goals and adapts as your life changes.
As a family financial planner serving Boston, Newburyport, and the North Shore, I help my clients do that.
Book an appointment with Scott.
Securities offered through LPL Financial, Member FINRA / SIPC. Investment Advice offered through Flagship Harbor Advisors, a registered investment advisor. Thrive Wealth Strategies and Flagship Harbor Advisors are separate entities from LPL Financial.
The opinions voiced in this material are for general information only and are not intended to provide specific advice or recommendations for any individual.
Asset allocation and diversification do not ensure a profit or protect against a loss. Investing involves risk, including possible loss of principal.