For many families, September can feel more like New Year’s Day than January 1st. The reason is that after months of vacations and chasing kids from one activity to the next, life finally gets back into its rhythm. School buses are back, and calendars start filling up. And, most importantly, parents can finally catch their breath again – school is back in session, thank the lord!
If you’re a Gen Xer, you probably know exactly what I mean. Summer has a way of putting everything else, including your finances, on pause. That’s why I think back-to-school season is one of the best times of year to reset.
As Labor Day closes out and school gets underway, vacation credit card bills start arriving, and summer spending habits become clear. And there’s still enough time to make meaningful progress before year-end! It’s a great opportunity to revisit your financial plan: increase retirement contributions if you’ve fallen behind, and finish the year stronger than you started.
Financial Oversight – Every Backpack Needs More Than Pencils
Parents spend weeks making sure their children have everything they’ll need for the school year. Ahh, the annual trip to Staples for all the fresh school supplies, then maybe a trip to Kohl’s or Gap for new sweatshirts for those cool September mornings.
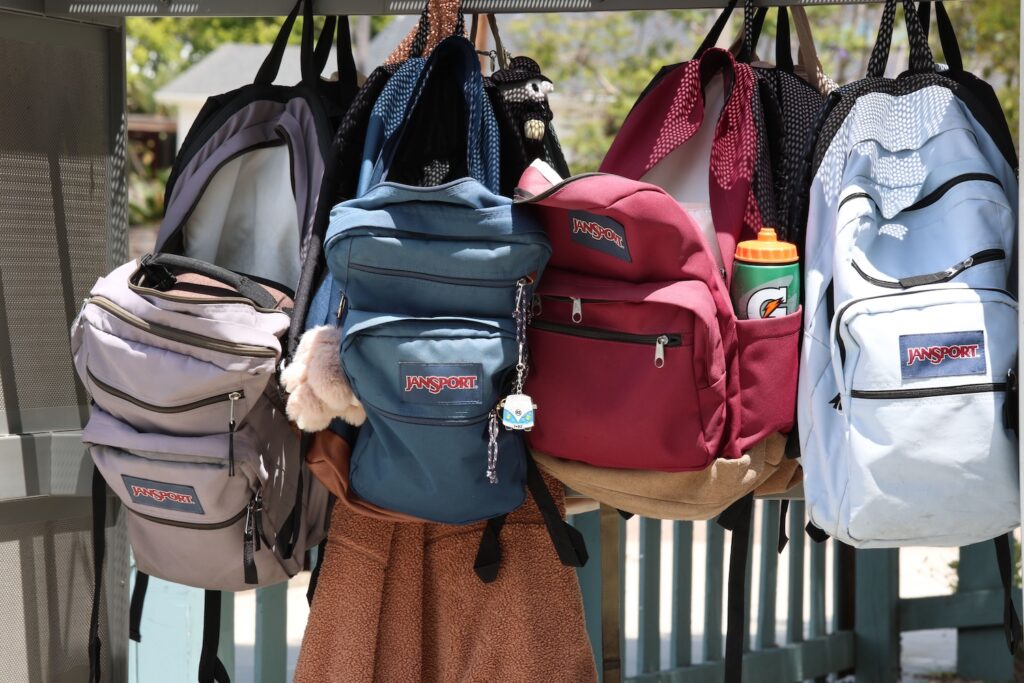
Now, no parent would pack a backpack with nothing but pencils and assume their child was prepared, right? Well, a thoughtful asset allocation strategy works the same way.
Stocks, cash, bonds, etc each have a different purpose. Just like every item in your child’s backpack contributes to a good school day, every investment should contribute to your long-term financial plan/goals.
Read about my Three Bucket Strategy, where every dollar has a specific job rather than simply sitting in one account.
Preparation Beats Prediction, Every Time
School days are unpredictable. One day your child comes home glowing from all the fun they had, and the next, they come home in tears from a bad social experience or feeling left behind in class. The markets aren’t much different, of course; they have ups and downs too.
No one knows exactly what next year will bring, which is why diversification isn’t about predicting the future; it’s about being as prepared as possible for the scenarios that may play out. A diversified portfolio gives you more flexibility when life doesn’t follow the script, just as a well-packed backpack prepares your child for whatever the school day has in store – a few pencils and a warm Lunchable isn’t going to set them up for success.
Don’t Let Your 401(k) Become an Old School Locker
Remember cleaning out your locker at the end of the school year (yikes)? Old papers and half-used notebooks; not to mention something that was last month’s lunch.
Retirement accounts can become surprisingly similar. Many people contribute faithfully to a 401(k) for years without ever reviewing how it’s invested. The money is there, but the strategy hasn’t evolved. As your career, family, and retirement timeline change, your portfolio should evolve too.
To all my fellow Gen X parents out there, you balance children, aging parents, and retirement planning all at once – you’re tough, but everyone needs help now and then to make sure you’re staying on the right track; that’s why I’m here.
“All Set” Isn’t Always Optimized
One theme you’ll hear throughout my writing (sorry if you know the drill but I need to hammer this home) is the difference between being all set and being optimized.
Being all set means you’ve accumulated investments, but being optimized means every investment has a purpose and still fits your life today.
Just as every child’s backpack looks a little different, every family’s financial plan should be customized around their own goals and priorities. There isn’t one perfect portfolio because there isn’t one perfect family. As the kids get the school year underway, consider giving your finances the same fresh start; there’s still plenty of time to finish the year strong!
As a family financial planner serving Boston, Newburyport, and the North Shore, I enjoy helping families organize their financial pieces so they work together in unison.
Securities offered through LPL Financial, Member FINRA / SIPC. Investment Advice offered through Flagship Harbor Advisors, a registered investment advisor. Thrive Wealth Strategies and Flagship Harbor Advisors are separate entities from LPL Financial.
The opinions voiced in this material are for general information only and are not intended to provide specific advice or recommendations for any individual.